What Happens to Credit Card Fees When You Refund a Retainer?
Business Owner Resource Library • 5-minute read
Have you ever had to refund a client's retainer—and realized the credit card fee you paid isn't coming back?
If so, you may have found yourself wondering who should be responsible for that cost.
Many service-based businesses collect retainers or advance payments before significant work begins. Clients may have the option to pay by check or credit card, and credit cards can make collecting those funds quick and convenient.
But accepting a credit card comes with a cost.
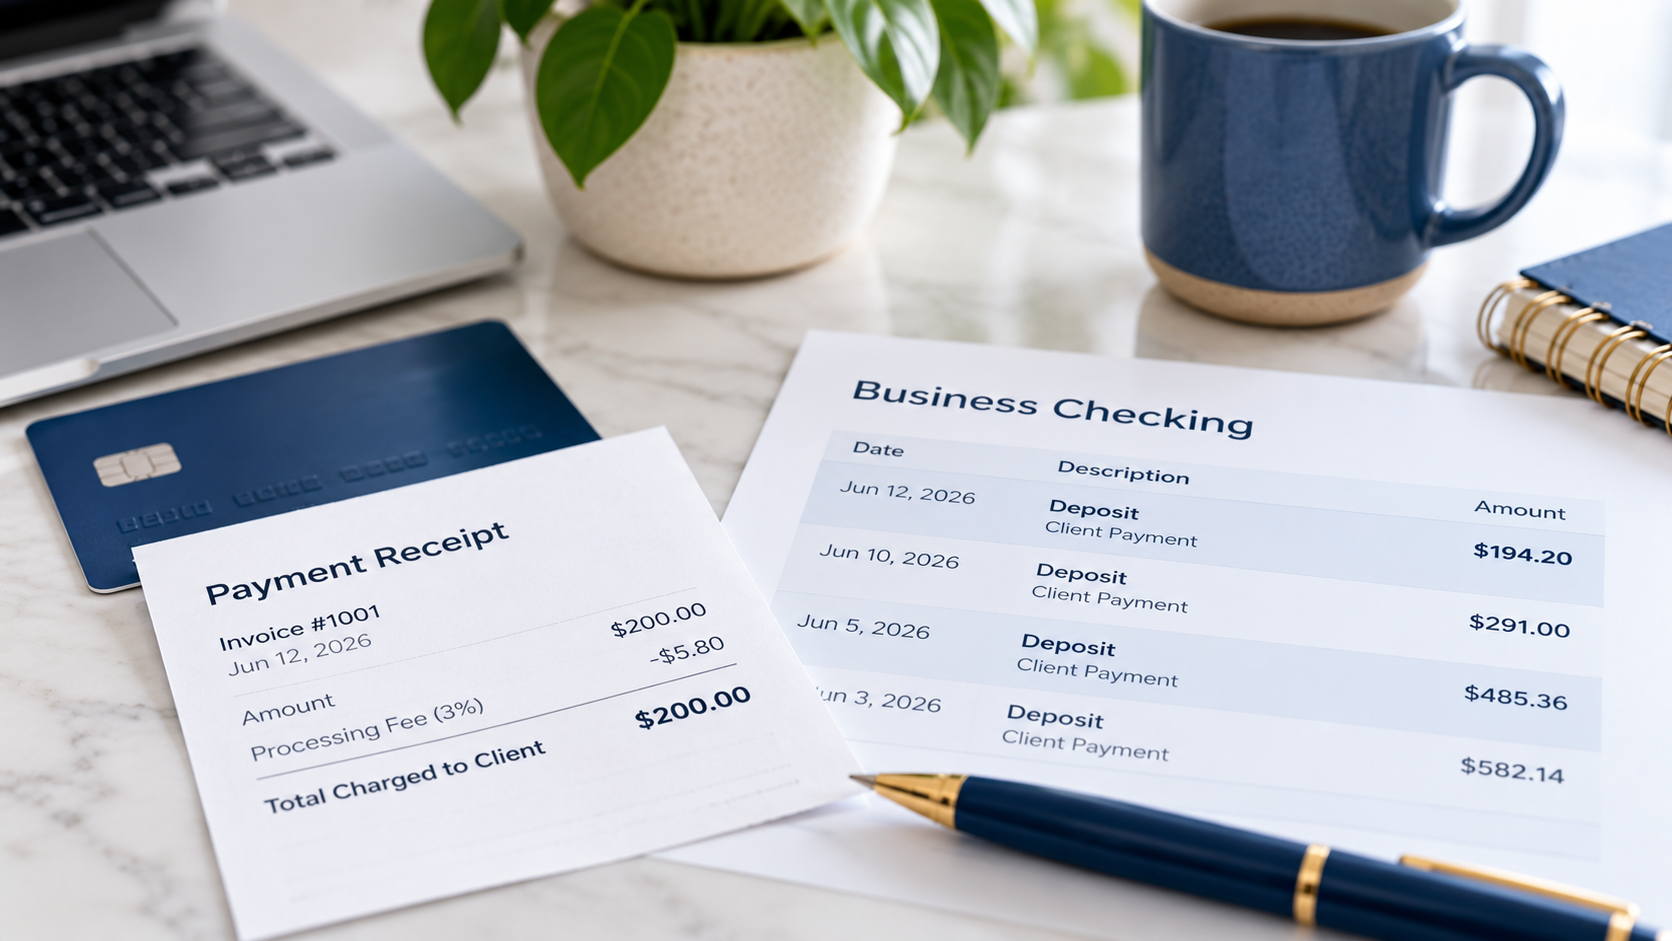
If a client pays a $3,000 retainer by credit card and the processing fee is 3%, your business incurs a $90 fee. If you later provide the services, that may simply be part of the cost of accepting credit cards.
But what happens if the work never takes place and you need to refund the retainer?
That's where things can get more complicated.
The Misconception
It's easy to think:
"If I refund the retainer, everything just goes back to where it started."
Unfortunately, that isn't always the case.
Depending on your payment processor and its refund policies, you may still have incurred some or all of the processing costs associated with the original payment.
That means you could return the client's entire retainer and still be out the credit card fee—even though you never performed the work the retainer was intended to cover.
The Reality
Credit card processing fees are a separate cost from the client's retainer.
That's an important distinction.
The retainer represents funds received for future services and remains subject to the terms of your client agreement. The credit card processing fee is a cost your business incurs for processing the client's chosen method of payment.
If you allow clients to pay by check without a credit card processing cost, but they choose to pay by credit card instead, it's worth deciding before accepting the payment how those processing costs will be handled if the retainer later needs to be refunded.
Your client agreement should clearly explain the policy.
Because laws, professional requirements, card-network rules, and processor policies can affect how these fees may be handled, the specific language in your agreement should be reviewed by the appropriate legal or professional advisor.
A Practical Example
Imagine you're a therapist who collects a $3,000 advance payment for anticipated trial-related services.
Your client has two ways to pay:
Pay the $3,000 by check.
Pay the $3,000 by credit card.
The client chooses to use a credit card, and your payment processor charges a 3% processing fee, or $90.
You now have:
Client advance payment: $3,000
Credit card processing cost: $90
A few weeks later, the parents settle their case and your services at trial are no longer needed.
The unused $3,000 advance payment now needs to be addressed under the terms of your client agreement.
But you've already incurred the $90 credit card processing cost.
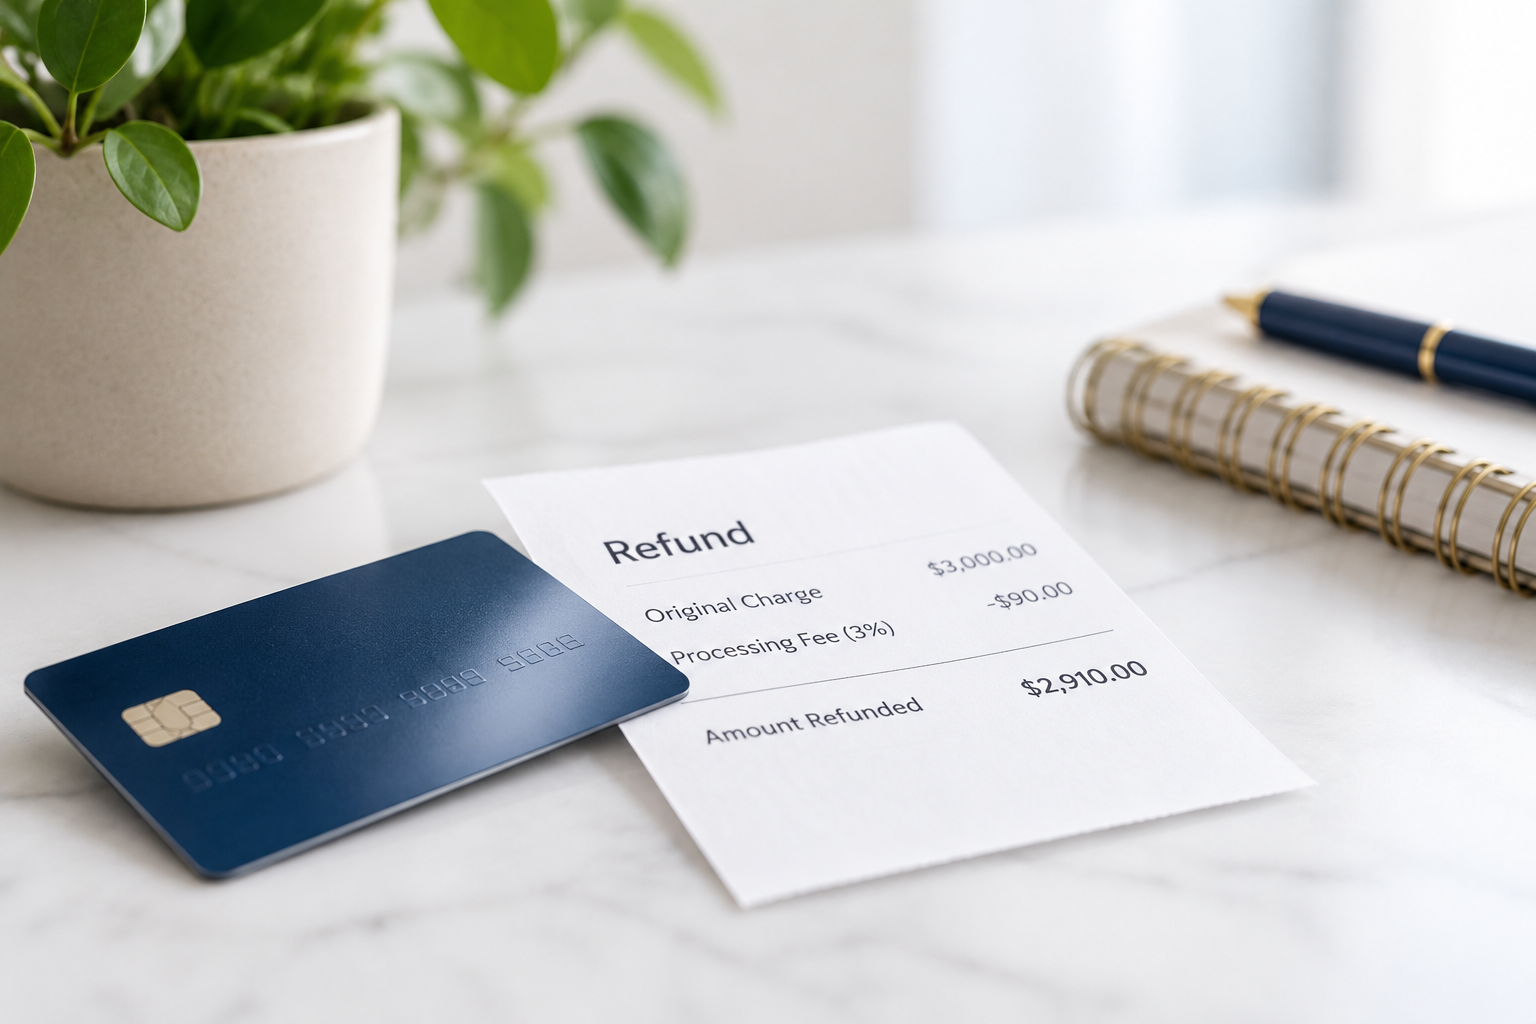
If your agreement appropriately provides that the client is responsible for that processing cost when an advance payment is refunded, the amount returned to the client could be:
Unused advance payment: $3,000
Less credit card processing cost: $90
Refund to client: $2,910
Without a policy established in advance, you may instead find yourself absorbing that $90 cost.
Why It Matters
Thinking about refunds when you establish your payment policies can help you:
Avoid unexpected credit card processing costs.
Make payment options and potential costs clear to clients.
Establish a consistent process for handling retainer refunds.
Reduce misunderstandings when an engagement ends earlier than expected.
Keep the bookkeeping for retainers, refunds, and processing costs accurate.
Most importantly, it allows both you and your client to understand what will happen before money changes hands, rather than trying to resolve the issue when a refund is already due.
Key Takeaways
Credit card processing fees are separate from the retainer or advance payment itself.
If clients can pay by check, they may have an option that avoids credit card processing costs altogether.
Don't assume that refunding a retainer means the original processing cost disappears.
Your client agreement should clearly address how processing costs will be handled if an advance payment is later refunded.
The specific policy should comply with applicable laws, professional requirements, card-network rules, and your payment processor's terms.
Good bookkeeping should separately track the client's retainer balance, any refund, and the related processing costs.
Important
Every business is different. This article is intended for general educational purposes and shouldn't be considered accounting or tax advice for your specific situation. If you have questions about how this topic applies to your business, I'd be happy to learn more during a no-obligation Discovery Call.
More Resources